Source: 3Q’24 Pension Monitor
Through September 30, 2024
Pension plan liabilities need to be measured and monitored regularly. Without knowledge of plan liabilities, the allocation of plan assets cannot be done efficiently or appropriately. The funded ratio/status of pension plans are present value calculations. Each type of plan is governed by accounting rules and actuarial practices, which determine the discount rate used to calculate the present value of liabilities. Single employer corporate plans are under ASC 715 (FASB) discount rates (AA corporate zero-coupon yield curve); multiemployer plans and public plans use the ROA (return on asset assumption) as the liability discount rate. The difference in liability growth between these plans can be quite significant (see 2022’s differential of 31.5%), which will affect funded status and contribution levels, and it may lead to inappropriate decisions.
The table below compares these different liability growth rates (based on a 12-year average duration) versus the asset growth rate based on the P&I asset allocation survey of the top 1,000 plans which is updated annually (each November).
| ASSET ALLOCATION | Q3’24 Return | Corporate | Public | Union |
|---|---|---|---|---|
| Domestic Stock | 22.1% | 12.6% | 21.9% | 22.2% |
| International Stock | 13.5% | 6.3% | 13.6% | 9.9% |
| Global Equity | 19.1% | 5.7% | 5.4% | 11.6% |
| Domestic Fixed Income | 4.5% | 45.4% | 18.7% | 18.2% |
| Global Fixed Income | 6.7% | 0.6% | 1.6% | 0.4% |
| Cash | 4.1% | 2.2% | 1.9% | 0.9% |
| Private Equity | 8.6% | 8.7% | 15.0% | 12.3% |
| Real Estate Equity* | -1.8% | 4.8% | 10.8% | 9.7% |
| Other | 4.5% | 13.7% | 11.1% | 14.8% |
| TOTAL ASSETS Growth Rate | 8.2% | 10.3% | 10.9% | |
| LIABILITIES Growth Rate** | 4.6% | 5.4% | 5.4% | |
| Asset Growth – Liability Growth | 3.6% | 4.9% | 5.5% |
Index Benchmarks: Domestic Stock = S&P 500; Int’l Stock = EAFE, Global Equity = All Country World; Domestic Fixed Income = BB Aggregate; Global Fixed Income = FTSE World Gov’t (unhedged); Cash = Ryan ALM Cash Index; Private Equity = 10-year return for the R2500 + 2%; *Real estate Equity = NFI-DP Index (one month lag); Alternative Investments and Other = CPI-U & 3%.
** Liabilities (corporate) = Ryan ALM ASC 715 discount rate and Liabilities (Public, Multiemployer) = 7.25% ROA
The graph below shows the contrasting annual differences of asset versus liability growth for corporate and public plans since 2015. The impact of different accounting rules (FASB vs. GASB) can create confusion, as reflected in the chart below.
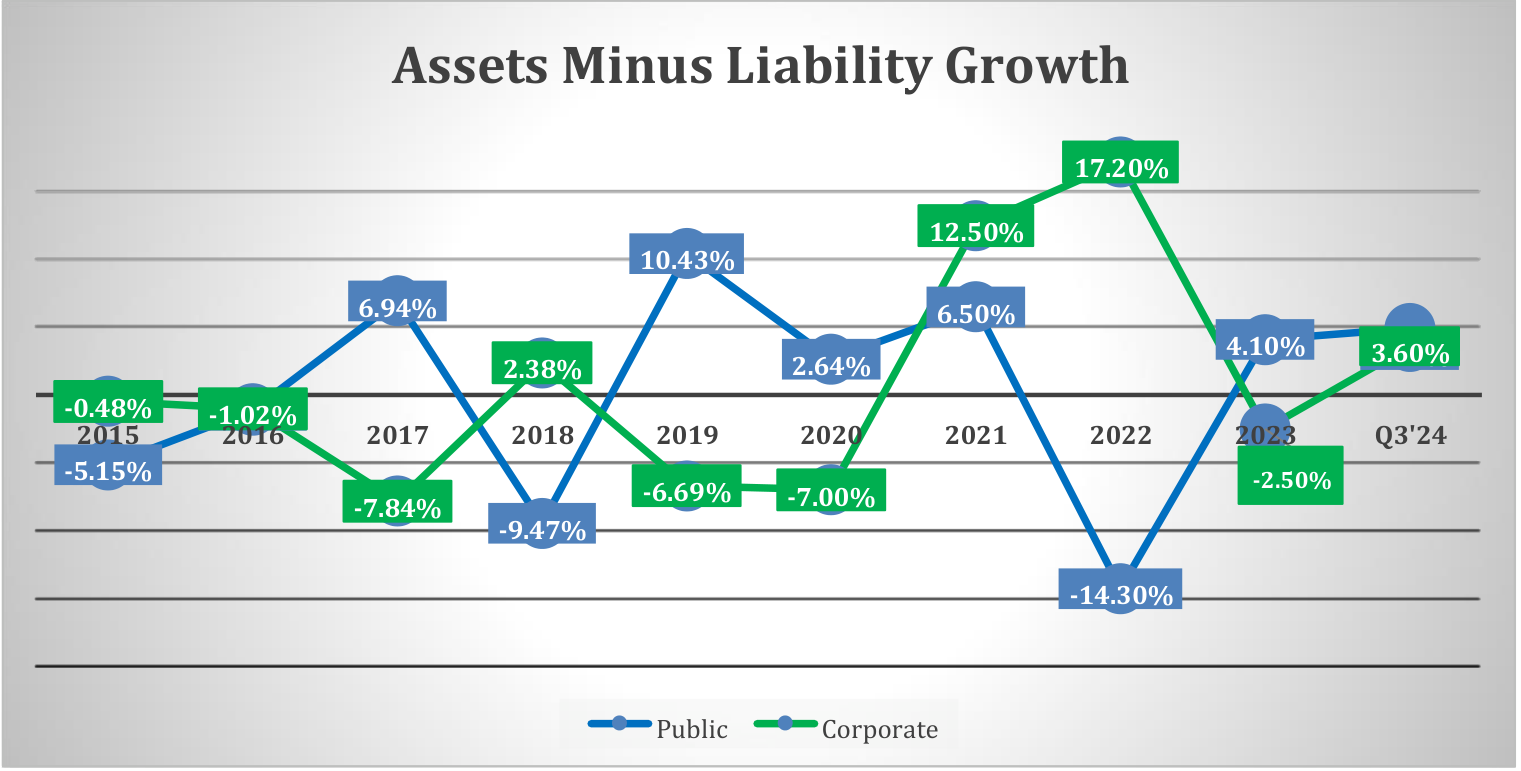
Footnote: The measurement of asset growth to liability growth is an annual calculation beginning on December 31, 2015. For periods shorter than 1-year, the observation is a YTD calculation.
With regard to Q3’24, Public pension funds (4.9%) have outperformed Corporate Pension plans (3.6%) by 1.3% on a YTD basis net of liabilities. The public fund and multiemployer discount rate using the average ROA appreciated by 5.4% (3/4s of 7.25% average ROA). This underperformance by corporate pension plans was primarily the result of a much greater exposure to US fixed income in corporate asset allocations (45.4%) versus both public (18.7%) and multiemployer (18.2%) and the far less exposure to US equities (12.6%) versus publics (21.9%) and multiemployer (22.2%).
There hasn’t been much of a difference in liability growth among the three pension plan types so far this year, as ASC 715 discount rates and the GASB discount rates (ROA) both showed positive growth during the first 9 months. The ASC 715 discount rates are market-based (influenced by interest rates), while the GASB accounting rules allow for the ROA, which provides a positive liability growth rate each and every quarter. As you may recall, we witnessed in 2022 how different accounting rules can have a major impact on a plan’s funded ratio/status, potentially leading to incorrect decisions with regard to benefits, contributions, and asset allocation decisions.